European data center power contracting has almost tripled since 2022
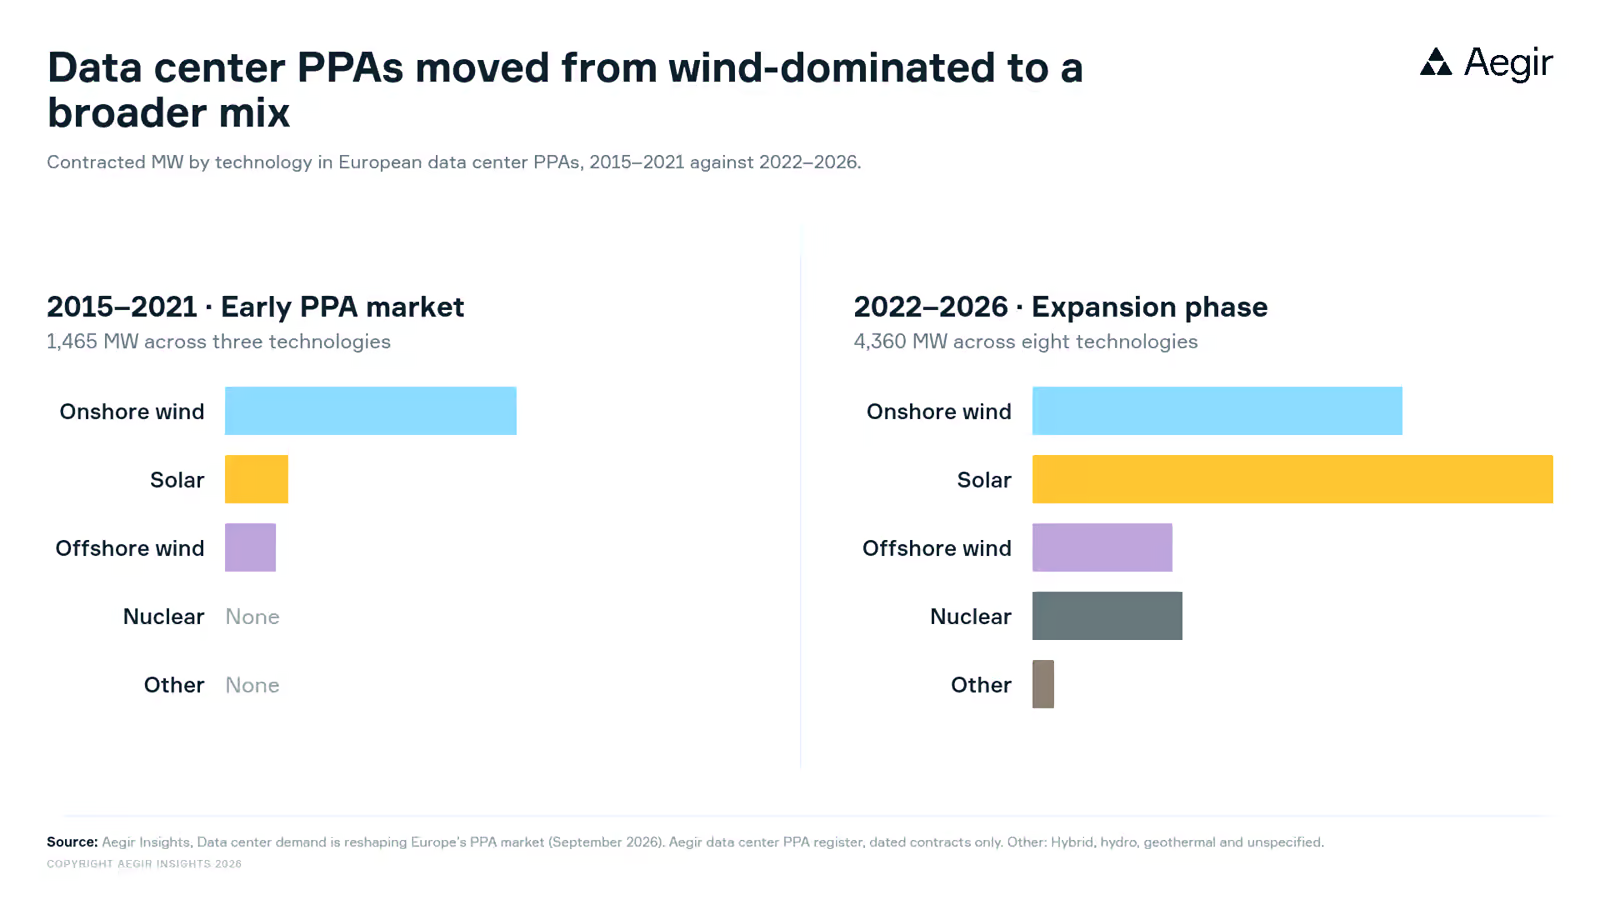
European data center power contracting has almost tripled since 2022, while the technology mix has broadened substantially. Since 2022, contracted capacity by data center operators has reached more than 4,300 MW across eight technologies, compared with 1,465 MW across three technologies in 2015-2021.
In a new analysis, Aegir Insights has looked at over 120 live data center PPAs in Europe, analyzing contracted capacity, technology mix and constraints.
Why is access to power driving data center procurement?
Access to power is becoming a key driver of procurement decisions for hyperscalers: Data centers can often be built much faster than their power supply. Increasingly, technologies with large pipelines and shorter delivery cycles are favored for power purchase agreements (PPAs), as are markets where generation and network capacity can be secured in time.
How has the technology mix in data center PPAs changed?
The technology mix has changed substantially. Onshore wind dominated the early data center PPA market, but solar is now the largest source of newly contracted capacity. Its large pipeline and shorter delivery cycle fit the timeline a data center is built on.
Before 2022, contracts covered onshore wind, solar and offshore wind. Since then, nuclear has appeared for the first time, alongside hybrid, hydro, geothermal and unspecified generation.
Where in Europe are data center PPAs being signed?
Contracting is concentrated in a few European markets. Ireland, the Netherlands, Spain and Finland account for close to 70% of contracted capacity, on very different power-system conditions.
For how Ireland now ties new data center connections to additional renewables, see Ireland's data center grid connection rule.
Where does offshore wind fit in hyperscaler power procurement?
Offshore wind fits hyperscalers at portfolio level rather than individual campuses. Its scale and timeline suit broader corporate procurement, while site-specific PPAs go to technologies that match a facility's delivery schedule.
Where to read the full analysis
Aegir Insights' new analysis goes deeper into data center power contracts across Europe, including a detailed buyer-and-seller breakdown, a contract mix overview and time-to-power constraints. Clients can access the report on the Aegir Intelligence Platform.
The contracts sit alongside the Aegir data center coverage and the renewables project database.
Want a glimpse of our analysis? Reach out for a walk-through.
Key questions on data center PPAs in Europe
How much power have European data centers contracted since 2022?
More than 4,300 MW across eight technologies, almost triple the 1,465 MW across three technologies contracted in 2015-2021.
Which technology do data centers contract most?
Solar is now the largest source of newly contracted capacity. Onshore wind dominated the early data center PPA market.
Why does access to power matter for data center PPAs?
Data centers can often be built much faster than their power supply. Technologies with large pipelines and shorter delivery cycles are favored, as are markets where generation and network capacity can be secured in time.
Which European markets lead data center power contracting?
Ireland, the Netherlands, Spain and Finland account for close to 70% of contracted capacity, on very different power-system conditions.
Do hyperscalers buy offshore wind for their data centers?
Offshore wind fits hyperscalers at portfolio level rather than individual campuses. Its scale and timeline suit broader corporate procurement.
How many data center PPAs did Aegir analyze?
Over 120 live data center PPAs in Europe.