Europe's early 2030s offshore wind pipeline holds 60+ GW of supplier opportunities
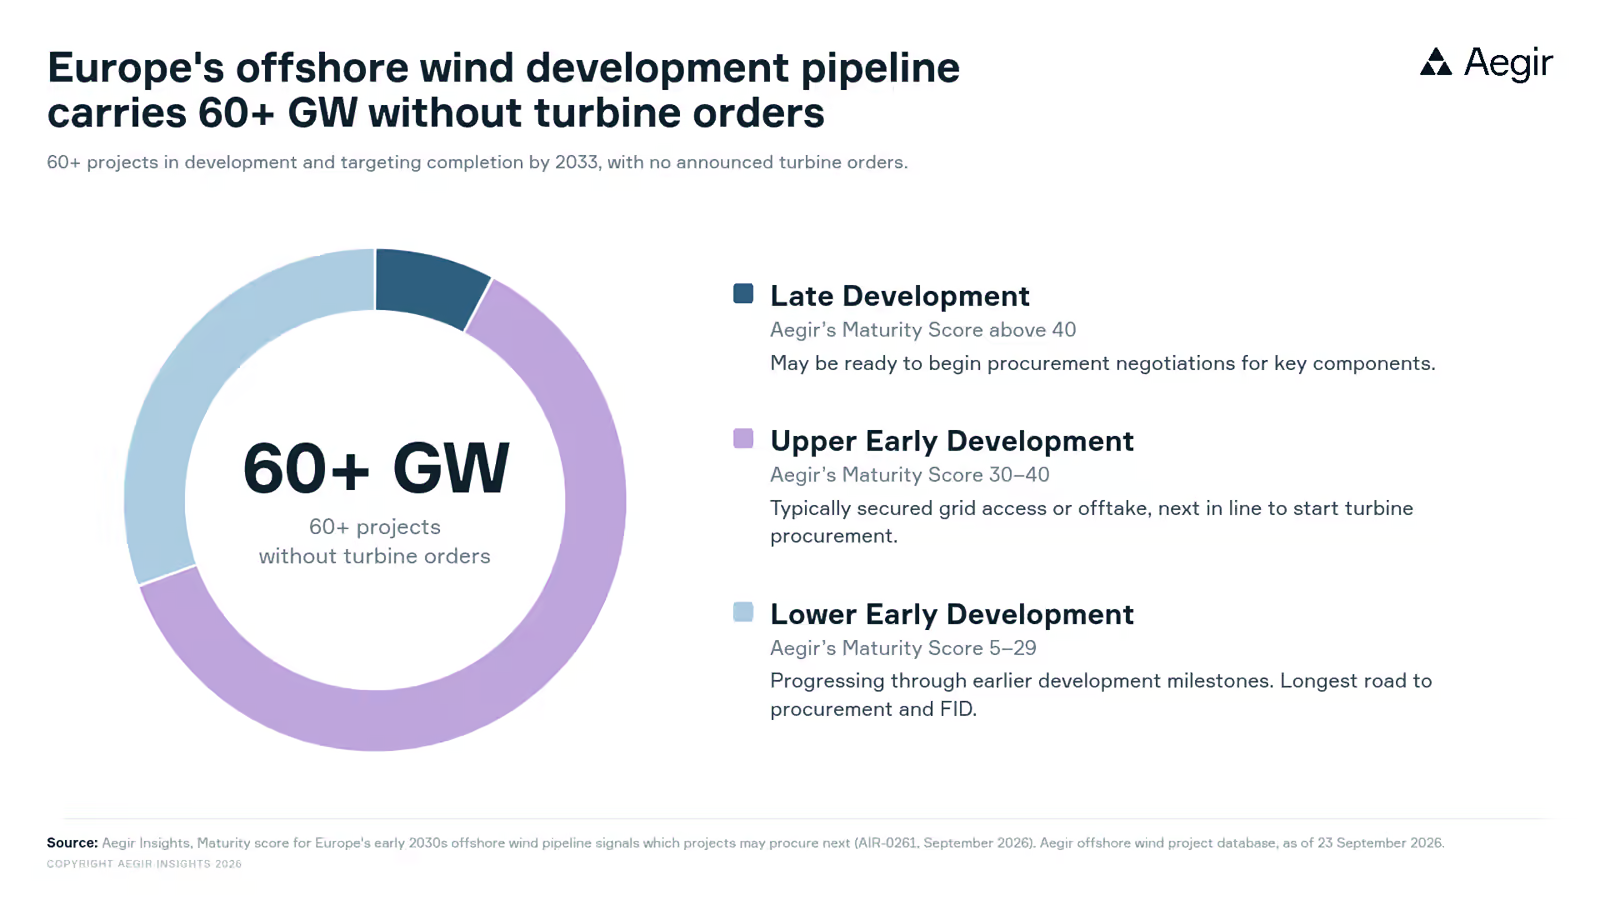
Europe's early 2030s offshore wind development pipeline holds more than 60 GW of potential supplier opportunities.
More than 60 projects with Aegir-expected CODs between 2028 and 2033 have yet to place turbine or foundation orders. These projects span from early development to late development. But which will procure next?
How does the Aegir Maturity Score rank offshore wind projects?
Every offshore wind project on the Aegir Platform now has a Maturity Score from 0 to 100, based on seven key development milestones. This makes it easy to screen upcoming opportunities, identify which projects are approaching their order windows and where suppliers should focus next.
In Aegir Insights' recent analysis, we dive into the pipeline of European offshore wind projects that are expected to reach COD by 2033 and have not yet placed a turbine or foundation order.
What do the development stages mean?
Late Development projects have a Maturity Score above 40 and may be ready to begin procurement negotiations for key components.
Upper Early Development projects score 30 to 40. They have typically secured grid access or offtake and are next in line to start turbine procurement.
Lower Early Development projects score 5 to 29. They are progressing through earlier development milestones and have the longest road to procurement and FID.
For how project maturity moved across the market last year, see movements in offshore wind project maturity throughout 2025.
Which projects could drive the next wave of orders?
Upper Early Development projects could drive the next wave of orders. Almost 40 projects with 40+ GW of open capacity, most of it in the UK and Germany.
Could a seller's market emerge?
A seller's market could emerge. Projects that would reach COD in 2031 and 2032, if they advance toward FID on schedule, hold 37 GW without turbine orders, which could prompt earlier procurement to secure supply.
Who holds the open capacity?
Future order volumes depend on a few markets and developers. RWE, TotalEnergies, SSE Renewables, JERA Nex bp and Vattenfall hold most of the open capacity.
Where to explore the pipeline
Clients can explore the Aegir Maturity Score, filter the pipeline to their specification and export the project list on the Aegir Intelligence Platform. Read the full analysis on the platform, alongside the offshore wind project database and the renewables project database.
Key questions on Europe's offshore wind procurement pipeline
How much European offshore wind capacity has yet to place turbine or foundation orders?
More than 60 GW across more than 60 projects with Aegir-expected CODs between 2028 and 2033.
What is the Aegir Maturity Score?
A score from 0 to 100 that every offshore wind project on the Aegir Platform now carries, based on seven key development milestones.
Which projects are likely to procure next?
Upper Early Development projects could drive the next wave of orders: almost 40 projects with 40+ GW of open capacity, most of it in the UK and Germany.
Why could a seller's market emerge?
Projects that would reach COD in 2031 and 2032, if they advance toward FID on schedule, hold 37 GW without turbine orders, which could prompt earlier procurement to secure supply.
Which developers hold most of the open capacity?
RWE, TotalEnergies, SSE Renewables, JERA Nex bp and Vattenfall.