Germany's onshore wind bottleneck has moved beyond permitting
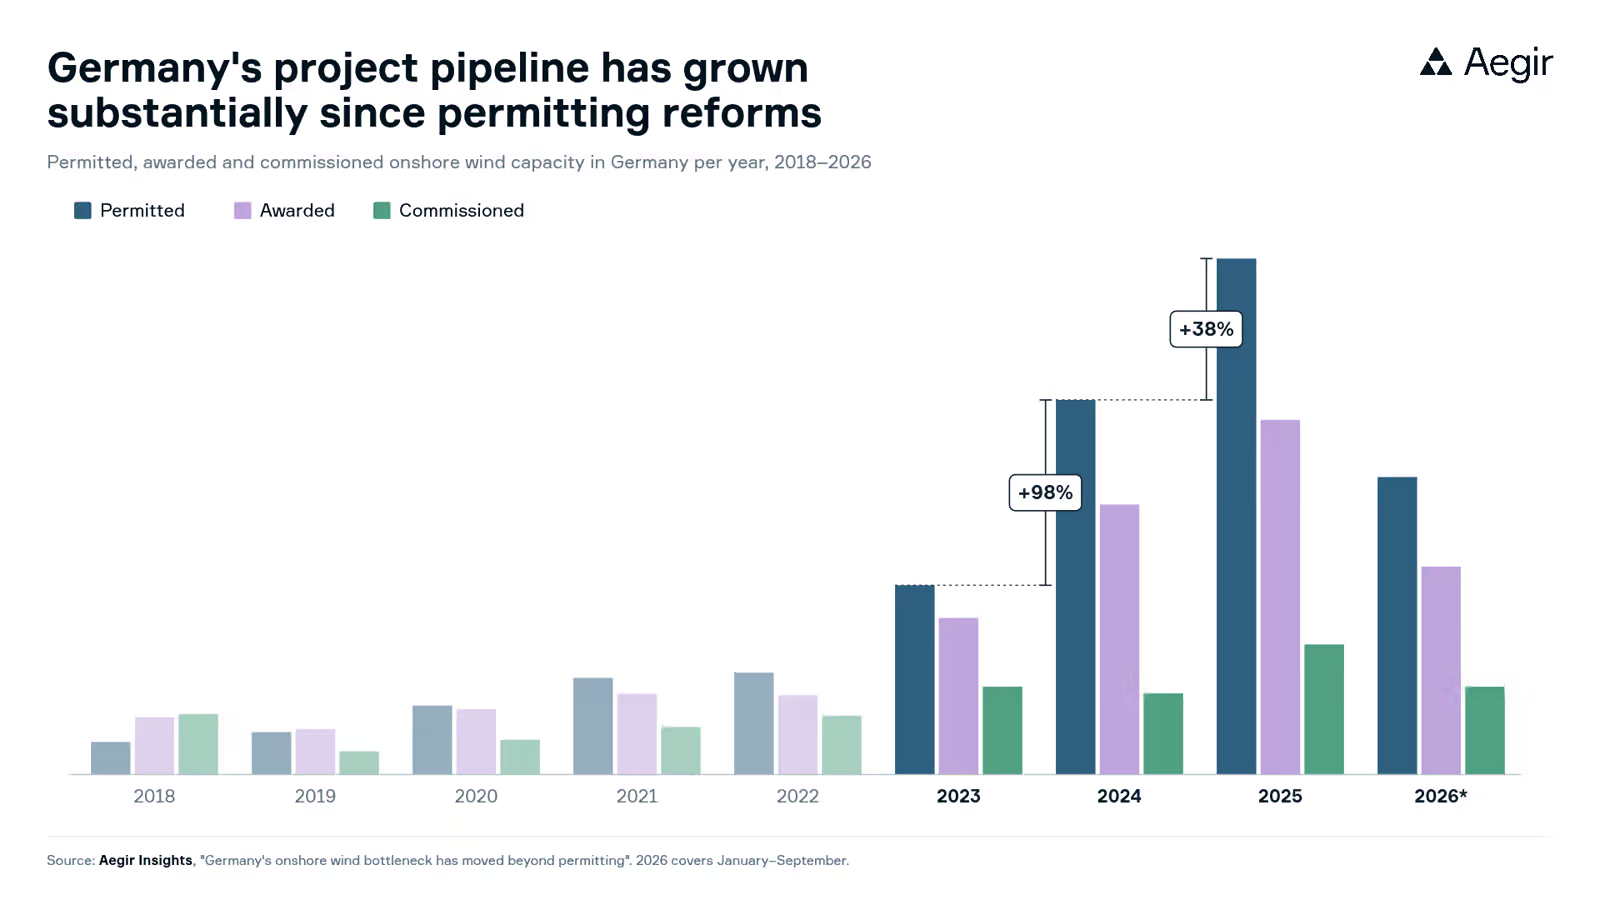
Germany has largely solved the first stage of its onshore wind pipeline: Building up a healthy pipeline of permitted projects.
Permitting has accelerated far faster than build-out.
Annual onshore wind approvals in Germany rose roughly fivefold from 2022 to 2025. Authorities approved over 20 GW in 2025, while commissioning reached over 5 GW. By mid-2026, more than double the 2025 volume was already permitted.
Auction volume now limits how much of the permitted pipeline can progress.
Since November 2024, auction volume has become a second constraint. Germany's August 2026 onshore wind auction was the eighth consecutive oversubscribed round.
More awards would help, but delivery remains a separate challenge.
The German Bundestag opened deliberations on the EEG 2027 and grid packages in September. The EEG 2027 draft proposes 15 GW of auctions in 2027. Even at that volume, the unawarded permitted pipeline could reach 30+ GW by the end of 2027 if recent permitting rates continue. Grid connection, transport and project economics will affect how quickly awarded projects reach operation.
Clients have access to a new report analyzing Germany's onshore wind pipeline from permitted to awarded and commissioned, the time projects take from permit to operation, the country's auction constraint and what the new EEG 2027 package could address.
For the wider auction picture, see our onshore wind auction database.
Reach out to us for a discussion: www.aegirinsights.com/contact