Re-tendering 9.5 GW of German offshore wind sites will not get them built under the draft WindSeeG reform
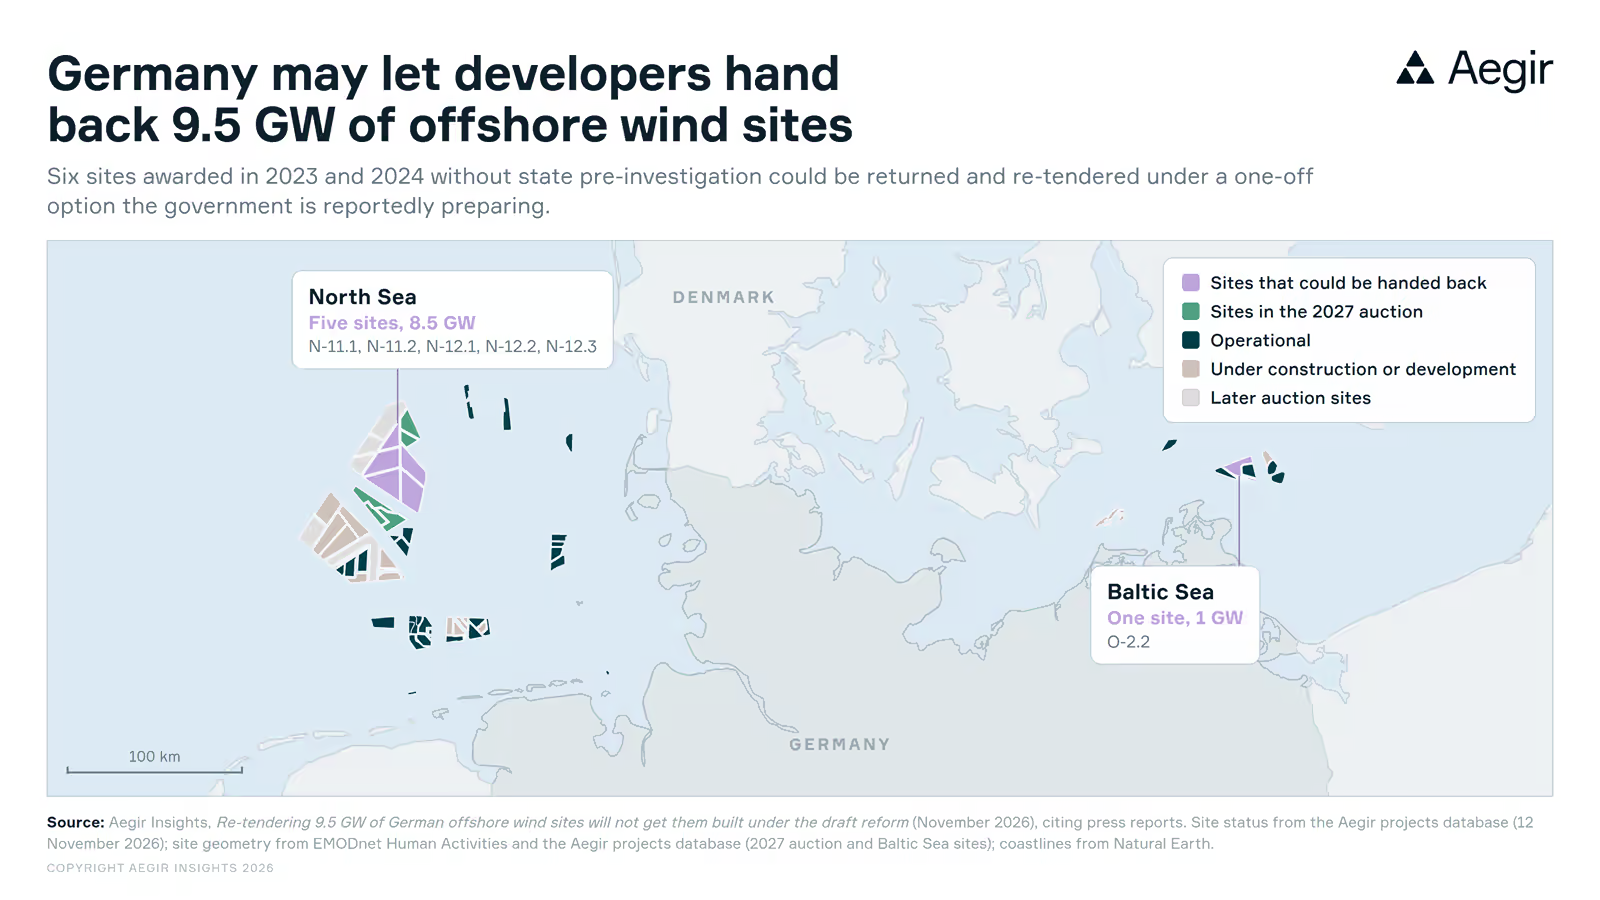
Germany may let developers hand back 9.5 GW of offshore wind sites won in 2023 and 2024. Would anyone take them on in a re-tender though?
Germany’s economy and energy minister signaled a return option for the struggling non-pre-investigated sites from 2023 and 2024. The holders bid about EUR 15.6bn for these sites, against strict milestones, and face merchant terms, with post-tax nominal project IRRs estimated at about 1-2%.
A return would make the sites available again. But would a new bidder take them?
What does the draft WindSeeG reform offer re-tendered sites?
Under the draft WindSeeG reform now before the Bundestag, sites that draw no payment bid go to a two-sided CfD round. Modeling based on the proposed reform does not close the gap for these potentially re-tendered sites:
- Short of the hurdle: At the draft ceiling price, Aegir Quant™ puts the five struggling North Sea sites at a project IRR just under 5%, well below the 7.5% Aegir uses as its standard hurdle.
- About 40% above the ceiling: At the draft ceiling price, no site reaches the return investors typically need. Each North Sea site would need a strike price about 40% above the ceiling, or a higher ceiling price that is also indexed.
- 40 GW comes two years late, at best: Germany’s site plan still assumes these sites help reach 40 GW by 2035. They’re already behind, and re-tendering from 2028 would formalize the delay to 2037.
What happens in the 2027 auction?
The 2027 auction is the real test. Next year, Germany tenders about 4 GW on five other sites (green on the map), not the ones that could be handed back, under the auction design in the draft WindSeeG reform. Aegir’s modeling finds their economics similar to those of the struggling 2023 and 2024 sites. If those bids fall short, a return only adds sites to a queue that is not maturing.
Clients can access the report on the Aegir Intelligence Platform.
Interested in getting a glimpse of this analysis?
Reach out to us: www.aegirinsights.com/contact
Key questions on re-tendering Germany’s offshore wind sites
Which German offshore wind sites could be handed back?
Six sites awarded in 2023 and 2024 without state pre-investigation, 9.5 GW in total: Five in the North Sea (N-11.1, N-11.2, N-12.1, N-12.2 and N-12.3, 8.5 GW) and one in the Baltic Sea (O-2.2, 1 GW).
What returns do the holders of the 2023 and 2024 sites face?
The holders bid about EUR 15.6bn for these sites, against strict milestones, and face merchant terms, with post-tax nominal project IRRs estimated at about 1-2%.
Would the two-sided CfD in the draft WindSeeG reform make the sites investable?
At the draft ceiling price, Aegir Quant™ puts the five struggling North Sea sites at a project IRR just under 5%, well below the 7.5% Aegir uses as its standard hurdle. Each North Sea site would need a strike price about 40% above the ceiling, or a higher ceiling price that is also indexed.
How would a re-tender affect Germany’s 40 GW target?
Germany’s site plan still assumes these sites help reach 40 GW by 2035. Re-tendering from 2028 would formalize the delay to 2037.